Houzz Logo Print
hzdeleted_20096495

Who writes Cheques :)

8 years ago
last modified: 8 years ago

So I took a mini survey of my friends. A few answered. Turns out grocery stores here DO accept them as forms of payment, yet nobody pays with them. (ETA: my friends mom is the exception)

Nobody pays their household bills with them.

One uses them to pay for her children's extra curricular sporting events

Two have never written a cheque in their lives (one is 28, the other will be 33)

One thinks the last cheque he wrote was when he remortgaged his house. He must use a mortgage guy, because I used my bank and never needed that. (ETA: nope! It was a void cheque for auto payment)

Oh heck............ here's the thread on my FB page (you can see it if you have FB, + you'll see any other public posts I have but nothing else - unless we are friends on FB)

https://www.facebook.com/debby.fraser

Comments (63)

  • 8 years ago

    I mostly pay on line bills and use credit cards everywhere if not cash. But my most recent checks have been to reimburse friends for buying show tickets, my dentist, my eye doctor, my taxes. Those for whom paying through the bank doesn't work. But I keep my check register going for all the on line bill payment and still balance it every month.

  • 8 years ago

    Annie, most banks will send checks on your behalf if you go to their "bill pay" function on the website. Checks can be sent to individuals as well as businesses large and small of any kind, including medical offices, etc.

  • Related Discussions

    What's the main difference between: paycheque and pension cheque?

    Q

    Comments (4)
    Hi Socks 1234 ... what was that other number, again, please? Many advisors suggest that as people get older, they should carry a smaller percentage of their assets in equities, where the values fluctuate substantially and concentrate more on investing where their principal is more secure, e.g. bonds, GICs. Trouble is - when you invest where your principal is guaranteed, there are two rats that eat your cheese. There's an entity that favours you with a question, each year ... and a statement. Regarding your annual income, ... "How much did you earn, last year?", and "We want part of it", ... ... are the messages that most of us get from the income tax people. And, if you invest your dollars where you want that touted guarantee that the number of invested dollars isn't going to shrink over the interim ... ... there's another guarantee that the folks who want to use your money (read "banks" or "bond issuers") never seem to mention ... ... the number of dollars of "principal" is "guaranteed" not to grow, either. So - since we've had to cope with inflation every year since the Great Depression of the 1930s, you need to take some of those dollars that they earned to put with the principal in order to preserve your purchasing power since the inflation rat nibbles off a corner of each of those "guaranteed" "principal" dollars every year. Know what? The rats eat first! You get what's left. Which in recent years has been very little ... if anything. I favour people, especially seniors, learning more about how money works, with a view to carrying a larger component of equity-based investments, where justified. I took the course that stockbrokers take (much more complex than the mutual fund guys need) and 6 courses leading to Chartered Financial Planner (passed only 5). Course revamped aiming at slightly different designation, Certified Financial Planner, I'd have needed to have started all over - at age 70 or so? I don't think so! I sold mutual funds (for a broker, so could offer a wider choice) for a short while, and for years have worked as a personal financial advisor, selling no products - no conflict of interest. Also, very few mutual fund managers justify their vaunted claim of more skillful money management, for they don't outperform the market averages. But in the U.S. they like to collect about a fifth or sixth of the average growth rate that the market produces, and in Canada about a fifth to a quarter of it. If individuals can develop the skills necessary, and the nerve to avoid getting upset if the market goes down some (i.e. sleep soundly at night at the time of a sliding market), they can usually produce a better result, long term, using a larger component of equities, I think. Maybe you noted a thread that I wrote here a few days ago asking that folks compare stock certificates (of one company) and rabbits for proliferation. I've written a number of threads on "Money Saving Tips", "Household Finance" and "Retirement" which will give you quite a bit of information about my approach to effective management of income and assets. If you have further questions, I'll be pleased to answer them. Good wishes to you and yours. ole joyful
    ...See More

    What's the major difference between paycheque & pension cheque?

    Q

    Comments (4)
    Our hearts aren't all cold, Marie ... ... the Alberta people ship down a lot of crude oil to run your vehicles, etc. ... ... plus gas to heat many homes. So we do, sort of, compensate for those chilly cold air blasts. Asking pay for the heating systems, of course. Not too much of the milk of human kindness in our hearts, it appears. Well, generosity, anyway. Of course, one can scarcely blame us ... ... for we've supposed to have had free trade across our border. But a few years ago your country's producers of timber, unhappy about Canadian lumber coming in, unfairly, they said, got a duty slapped on. When the Canadians took the issue to the evaluation tribunals ... ... they won the point. Five times they won it. Then ... the U.S. Ambassador up here said that we need to talk about the issue. Yeah, right! If you're a rabbit, sleeping next door to an elephant ... better keep one eye open! So ... the 5 Billion or so that had been collected was divvied up - about 4 billion sent back to Canada. And they kept the One Billion ... that some Canadians said was given to the timber boys! By the way ... have you noted how much these primary election bashes must cost ... and that's just to select the candidates to run for the Presidency? Anyway - have a good election year! We may be having a federal election up here shortly, for there's a minority parliament in place now, which usually results in the guy in power making friends among the opposition. But our current Prime Ministr is very much a run-your-own-show kind of guy. Right now our federal treasurer is speaking to parliament, presenting the Budget for the coming year. He's been running around for weeks telling how poor they are, and not to expect good news, etc. I have some errands to run, so guess I'd better go get shaved. Hope we don't get skinned, about now! Better turn on the radio in the bathroom, I guess. Have yourself a great day - it's snowing here and they're talking storm, so I hope that I get home safe and sound, later tonight. ole joyful P.S. Just announced a new tax-reduction investment system, aimed at folks nearing retirement. o j
    ...See More

    For stay-at-home moms who write well . . .

    Q

    Comments (0)
    (and I think we have quite a few of them at the KT....) I ran across this ad in my daily freelancing search. It looks like a nice opportunity for a writing mom who'd like to earn some extra money.
    ...See More

    The cheque is in the mail!

    Q

    Comments (3)
    You never know what a dog is going to do when the owner walks away. I am glad your husband is getting a settlement, don't know about the Canadian laws, but just don't sign any releases until you know everything is OK. Like you say, the leg still bothers him, so She (dog owner) might have to pay additional medical expenses. Glad it he is better. Marie
    ...See More
  • 8 years ago

    I write about 5 a month

  • 8 years ago

    Well, I use checks for almost every thing. Don't carry much cash(maybe 20$) so I write 20 or more checks a month.

  • 8 years ago

    We cruise a lot, thus I have set up most things to be an automatic payment. I pay our estimated taxes with checks and our cat sitter, too. If there is a handyman or women doing something that I cannot safely do (electrical), then that person gets a check. Otherwise, it is all automatic.

  • 8 years ago
    last modified: 8 years ago

    A cheque annually for auto, tenant in house insurance, and quarterly for house rent.

    Contributions to a political party must be by cheque or other yraceable instrument.

    I contribute to some distant churches with whom I feel an ongoing connection by cheque.

    I used to contribute to quite a number of charities by cheque. l still contribute to a few charities by cheque, but for several years I have transferred stocks that have appreciated in value to a charitable foundation (United Way in recent years) and give them a list of charities to which I wish to contribute.

    That allows me to avoid paying tax on the capital gain.

    ole joyful

  • 8 years ago

    All my monthly bills are paid by check which includes my credit card purchases. I use cash for lunches out, grocery items I don't have delivered, tips, hair salon, gasoline, library fines, and "walking around" money. Plus the occasional flutter at the local casino and cash for handyman jobs.

  • 8 years ago

    I never write checks. I have no reason to with everything being electronic now. On the rare occasion I do need to submit a check as payment, like Elmer, i use the bill pay function from my bank. You log onto your bank's website and find "bill pay." You enter the recipient's name and amount, and the bank sends the recipient the check while debiting my account.

    If I want a paper print out of checking transactions, I just download a spreadsheet into Excel, and voila! there's the list of all transactions.

    User thanked sephia_wa
  • 8 years ago
    last modified: 8 years ago

    Decades ago I was advised to 'run everything through your checkbook'. I'm still writing about 100 checks a year. I like having instant access to my 'records' -- my check registers. I don't have to turn anything on or make copies of anything. It's all there, easily portable.

    While I was preparing our house for the painters to descend upon it next week, I removed private papers. One of the things I discovered was my stack of 50+ years of checkbook registers. I had to tear myself away from 'memory lane'. Who needs to keep a diary? Our whole married life is in these little one-line entries. I know that has changed, as I no longer write a check for as many individual purchases -- a baby carriage or the sapling that is now a big tree -- but I will miss that personal window to the past.

  • 8 years ago
    last modified: 8 years ago

    Decades ago, chisue, there was no electronic banking in the US, so the advice "put it in the check register" meant don't issue checks without keeping a written record of them. Don't look at it as a permanent technique to continue to follow forever, ignoring newer and better alternatives.

    Finding historical information in well used check registers is tedious and uncertain. Even an electronic spreadsheet record of transactions (and there are many other alternatives too) as sephia notes, that can be searched for instantaneous answers, provides information with far more facility than the old fashioned way.

    Decades earlier, you could go to town with a horse cart without turning anything on. Today, you need to turn on your car. I'm not sure I get the obstacle you're alluding to. Anyone here reading or making comments is using a device from which income and spending records can be immediately accessed, from more financial institutions than just one bank's checking account shown in a check register, no matter where the user is. If you did that from Hawaii, you could access information that's otherwise unavailable because it's at home in Illinois. It's okay if you choose to do it a different way but recognize many people have found newer approaches to be easier and more useful. I sure have.

  • 8 years ago


    I pay most bills online (no automatic payments) and write maybe 5 checks a month. Always carry cash, but pay for most retail transactions with credit cards. I keep a running check register for all transactions and balance every month. It's a mental exercise for me more than anything.

  • 8 years ago
    last modified: 8 years ago

    Another check writer here. I only use credit cards for gasoline, buying on line, and eating out but pay entire bill every month.

  • 8 years ago

    There was a similar thread the other day. We don't write as many checks as we used to. Mainly, I write them for the kid's activities at school and lunches. It irks me that I would have to pay an extra 2% to pay for school lunches online.

    I grew up using cash and do well with it. Most of my cash goes to the kids these days. Everything comes with a fee and we are often expected to have exact change.

    I quit highlighting my hair because it was getting too expensive. I sometimes get my eyebrows waxed. The places around here want the fee and tip paid in cash. I guess it could be the credit card fee for some, but I think some of these people also aren't reporting their income.

  • 8 years ago

    I write about 2 or 3 checks per month. I use my debit card. We have another debit card for travel and I put money in as needed online. My husband has a business and writes about 100 or so a year. I talked him into getting a debit card a few years ago and he does use it at stores now instead of carrying a check book.

  • PRO
    8 years ago

    I pay every bill online. I write checks at the hairdresser (cash or check only!), and to pay my Estimated Taxes. It's SO much easier! I can see exactly who has been paid and when, and it's a breeze when I'm gone for over 4 weeks each summer. I would NEVER go back to the old way!

  • 8 years ago

    I write 2 checks now, one to the local water company because it costs extra to pay on-line and Sprint because someone stole a phone using my info on their website so I requested a paper bill from now on.

  • 8 years ago

    I use checks at the gas station, church and to pay cable, cell, light and credit card bills, all other things I use my debit or credit card.

  • 8 years ago
    last modified: 8 years ago

    I write maybe four checks a year. All bills are paid through the credit union's bill pay. I use credit cards for daily purchases like gas and groceries, with a cash back credit card. We own a debit card, it's in the safe. Cash for very small purchases.

  • 8 years ago

    I use checks to pay for the handyman's work, for medical bills/co-pays, for property taxes and for the water company which charges a fee for bills to be paid online (no thank you). I use cash to pay for personal appearance services and groceries.

  • 8 years ago

    Wow! I'm really surprised at how many cheques are written. I honestly think the last time I wrote one was to pay my kids school fees 12 or 13 years ago. I've used a 'void' cheque to get direct deposit for my pay at work. I do everything online. I don't even go to the bank to cash a cheque anymore. I take a picture of the front and back with my phones banking app and it gets deposited. From my couch! At home. :) I hate going inside a bank. HATE it. They get robbed. By bad people. lol I did get a cashiers cheque back in November from our joint account to pay off my house that had it's mortgage through another bank and I hated that I had to go inside not one, but TWO banks in one hour! I even asked if the bank could electronically transfer that money over for me and they said they couldn't. Cashiers cheque was the only method. :( Technically, it was the only cheque since the kids were in school written, but the bank wrote it. LOL

  • 8 years ago

    I quit about a year ago. I realized I was better off, and had a better papertrail without them. I get money orders if there absolutely has to be a check. Why I went paperless? The schools would hold onto my checks forever. One check went months without cashing. No one goes to a brick and mortar place any more and it's just not efficient to go that route any more.

    :(

  • 8 years ago

    "No one goes to a brick and mortar place any more and it's just not efficient to go that route any more."

    Please do not make statements like this.........it is simply not true! You may not personally visit a brick and mortar bank but many others do.......and quite regularly. Otherwise, one would be hard pressed to explain those lines at the drive-thru window and the full parking lots :-)

    My bank is not large nor is it local. There are only two branches in my state and neither is located very conveniently for my current location. It was originally, under a different name, and only blocks from my previous residence. Now it is an hour long trip and a ferry ride :-) But when in the area I do still stop by to conduct any current banking business. I sometimes get asked why I do not change to a more convenient banking institution but I do not care to be an anonymous account holder among millions of others. I can call my bank, identify myself and know exactly to whom I am speaking and they know me. And my business and my pets and family. That kind of personalized customer service is very hard to come by and I for one do not care to give that up just for the sake of easy access or so-called "efficiency".

  • 8 years ago

    I am an "older folk" and do not write checks. Occasionally, I have used a plumber who won't take a credit card. However, the contractor who put in my kitchen counter tops advised me that when a plumber, electrician, etc., would not take a check to quite using them. He said this is because of identity theft. He said he personally will never use someone who will not take a credit card. I do write a check for my car registration (they charge an exorbitant fee for using a credit card). However, for property tax, I do use a credit card even though a fee is charged; I use it because the rewards I earn for the charge far exceed the fee for using the credit card.

    I was credit card free for quite a number of years, and then discovered how foolish it was simply because I had no credit scores (using the bank debit cards builds up no credit score). When I learned that, I started using credit cards again. It was difficult to get the first one since I had no credit scores. Will never make that mistake again, and have taught my grown children and my grown grandchildren the lesson I learned and told them to get a good credit card, but use it diligently.

  • 8 years ago

    "I can call my bank, identify myself and know exactly to whom I am speaking and they know me. And my business and my pets and family. That kind of personalized customer service is very hard to come by"


    What benefit derives from this? I'd suggest nothing at all, they can't do something for you that they wouldn't do for every other customer with the same account relationship as you have, whether they know their dog's name or not.


    My two main banks are thousands of miles away and I do all my interactions over the internet. In the rare event I need to call them, I identify myself and they know exactly who I am and can help me promptly.


    Some of the sentiments in this thread are similar to those in the "older people" thread, in that some of you are saying "I do what I do because that's what I do". If that works for you, great, but don't you ever wonder what you might be missing if you were open to try something different or new?

  • 8 years ago

    The benefit is obvious - if my bank is not local and I call for any information - which I have to do often - I do not have to jump through dozens of hoops trying to identify myself satisfactorily before they will release any information. I am a person to them.....not just an account number. And if something is up with my account, they call me. How many other large commercial banks will do the same?

    And I have to say that I really resent the implication if one does not follow the same mindless routines as everyone else and immediately adopt their preferred practices, one is somehow mentally deficient or behind the times. You want to use the Internet for all your banking needs??? Good for you! But do not dismiss others who might prefer a more personal, face-to-face approach.

    Elmer, many of your comments are meaningful and helpful. But the self-righteous attitude that your way is the best way that comes through most of them is extremely off-putting. I divorced my ex for just such a similar attitude (and he was seldom correct but would never, ever admit it). Your points would be made and taken much easier if you would temper that attitude.

  • 8 years ago
    last modified: 8 years ago

    garden, I'm direct and confident but don't intend comments to be self-righteous. Sorry if you view them that way.

    If you like face to face contact, great. My experience is very different. The bank that I closed an account in had plenty of people in the local branch to have face to face contact with (for those rare times I went in). If you put all of them in a room, they'd together have trouble answering basic banking questions. I usually had to call in to HQ anyways (and this was with a premier account status) to talk to people with more knowledge. This was a mid-sized regional bank that touted personal service, especially for customers with top tier status. They sucked.

    Banks have security procedures for log-ons and phone calls to protect themselves and customers, they're not hoops to jump through. I've never found any to be onerous. The average person I reach over the phone at my banks that are oriented for internet customers, in the rare instances that's necessary, are more knowledgeable and more helpful than the drones I've encountered in bank branches.

    I wonder how it is you think you know what the experience is for something you've never done before. And why you view what many people do to be mindless while what you do is thoughtful?

  • 8 years ago
    last modified: 8 years ago

    gardengal, It's was an observation and an opinion. I'm sorry you don't agree? But I do know they have fewer people in the parking lot and I can walk right up to a teller at any point, at any bank (I do business with three different ones, including my mom's) any day. It's not like it used to be? And Nashville has grown tremendously. It should be far harder to do what I can easily do? I didn't mean to get your cockles up.

    What truly disappointed me on bank staff, the last time I went into a place that required actual help (not an ATM)? I sat down with the person handling my son's CD, with them doing everything over the phone, using the prompts, asking me all the stuff I could've answered over the phone myself. So I no longer bother. Nowadays, I eChat with tellers. It's not the same as it used to be on this side of it. It does make me sad. I liked the personal interaction, but I don't understand why you think it's "simply not true" as though I am lying about my opinion. Take heart. I don't hate you, and I respect your opinion, even if we differ.

  • 8 years ago

    Some questions:

    Are you confident that all the components of electronic connection will always work seamlessly? How about at the 'other end' of the connection? (The Spectrum internet service at our Maui condo is unreliable. It took me ten minutes to get online to the KT this morning.)

    How private are business transactions by cell phone? (I read everyone in China -- even farmers in remote villages -- do ALL their financial transactions on their cells.)

    Do you keep some cash or other instrument of trade that would keep you going over a period when power or the internet was 'down'? (Yes, we did get the *alert* about the missile strike! LOL)

  • 8 years ago

    See, that's the thing chisue, I didn't want to do my CD business by phone, and yet, there we were conducting it by phone. I don't think we can outrun technology. It has us by the wires.

  • 8 years ago

    With my husband's conservatorship I have to write checks no debit cards allowed. On an average two a month. Beside that only the property taxes and gifts. Thank you gardengal.

  • 8 years ago

    I write checks for memorials, charitable contributions, ISP and the water bill. Our water company wanted to add a surcharge for the convenience of direct draft. I declined.

  • 8 years ago
    last modified: 8 years ago

    maifleur, how about payments by bank bill pay or bank issued checks, seems like they would be the same?

  • 8 years ago
    last modified: 8 years ago

    Elmer. I follow the guidelines set up by the probate court. http://www.circuit7.net/documents/probate/pro400/p422.pdf

  • 8 years ago

    rob, it didn't get my cockles up :-) It is just that your experience does not match mine. The banks in my area are almost always busy and standing in line is SOP......just like grocery stores, they never seem to have enough staff or windows open to service their in-person customers without them waiting in line. So when you say "no one goes to a brick and mortar anymore", I have to say it is simply not true.........obviously people do!! Maybe just not as much in your neck of the woods as they do in mine.

    Elmer, this little paragraph........."If you put all of them in a room, they'd together have trouble answering basic banking questions. I usually had to call in to HQ anyways (and this was with a premier account status) to talk to people with more knowledge. This was a mid-sized regional bank that touted personal service, especially for customers with top tier status. They sucked."........pretty much sums up the reason behind my comment. What an incredibly condescending and superior attitude!!

  • 8 years ago

    I guess I am old fashioned. I still write checks. I use my credit card for most purchases, but I pay the monthly balance with a check. So why don't I make more use of electronic payment. Maybe I'm a control freak; I want to have the control of taking money out of my bank account. I abhor the practice of automatic deductions from my account. It seems that these days everyone wants to automatically extract money from my account.

    I would gladly pay electronically, except it has become the practice of magazine subscriptions and many others to says just sigh up and never worry about missing a payment again. We'll just automatically extract money from your account when i comes due. The electric company has the same attitude. I say NO. Its too easy for me to forget a year later what I may have subscribed to, or I might have a beef about a payment when the goods or service did not arrive. I will set up an account where I must take action to pay the a bill. I do not want that part automated.

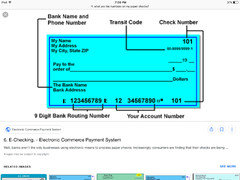
    The second reason is it is assumed that I will always have a working computer with a decent internet connection. That's a false assumption. Home computers can fail at the most inconvenient time. What if I decide that my budget cannot afford a replacement computer. I do not want to deal with this hassle of not having control of my bank account. Furthermore, I jealously guard the distribution of the routing number and account number of my checking account.

    However, I have moved large sums of money electronically. I found that was a convenient method when I needed to move a large sum from my account to my daughter's account particularity when her account was 800 miles distant from mine. The transfer took place in a few seconds and confirmation arrived a short time later after the systems made a few checks on account balances.

    I am more of a fuddy duddy than I had ever imagined I'd be - I do not have a smart phone. I make do with an ordinary flip phone.

  • 8 years ago
    last modified: 8 years ago

    I looked through that link. Debit card payments are allowed if the relevant bank statement and a purchase receipt are submitted. Since you've said that source documents are needed to be submitted anyway, that would suggest debit card payments are not viewed differently than checks.

    This is outside of the mainstream of what I did, though one of my aunts did have a conservatorship. I have to say the rules of this judge are needlessly old fashioned. I looked up probate and conservatorship rules for some local counties in my area and the reports they require are more along the lines of accounting analyses. Source documents are not required to be submitted. Too bad you have to deal with that, it's unnecessarily onerous. Any chance of moving the conservatorship to a different jurisdiction, you're likely paying for accounting or legal fees that really aren't providing much value to you.

  • 8 years ago

    Automatic deductions for bills is different then online bill pay. With Bill Pay, you pay your bills when you want to. My bills still arrive at my house in the mail. I pay each one using the BIll Pay at my bank. No paper checks, no postage, immediate knowledge of my balance after the payment is sent.

    Every person/company that receives your paper check has your routing and account number.

  • 8 years ago
    last modified: 8 years ago

    gardengal, I've had the experience of running into dummies at more banks than I want to think about. Maybe I'm dumb too, just not as dumb as they are. How else better to describe it?

    One banking brain cramp I once experienced was when I wanted to deposit a check I'd written, payable to my son, in his bank account. A bank I didn't have an account at myself. I had his name and out of state address (duh), account and routing numbers, a filled out deposit slip, and handed them to a teller. She asked if I had ID, I showed it. She called over a "supervisor" who politely took me over to her desk and told me that I could not make a deposit to someone else's account. I said "Really? Since when?" The response was "That's not permitted, only the account owner can make deposits." I said "Isn't your paycheck deposited in your account, how is that done then?" "Well, that's different". Me "How so? It's the same. Please let me speak to your manager". She came over, same story. I got in the car, drove a few miles down the road to another branch of the same bank and made the deposit without incident. Tell me what you think of that.

    PS - if every time you go to a bank you have to stand in a long line, wouldn't you rather try doing your banking a different way to avoid wasting time and getting irritated?

  • 8 years ago
    last modified: 8 years ago

    Not a chance of moving to a different county. Hard to get a change of venue with Probate issues.

    One thing about the automatic payments by check not ACH is that if you go on line and look for copies of the check sent you may not find it only a line item showing an automatic check. Things may have changed because that was a number of years ago. If something would happen like your payment being applied to another account and they ask for a copy you may be out of luck. Easier to do ACH with your payments than use the bank check.

  • 8 years ago

    Hmm. With the two banks I've done bank checks with, there are images available of the cleared and endorsed check exactly the same as if I had written a check myself. With an ACH payment, it's just the one line entry in the statement as you describe. But that would correspond to what this judge says is acceptable for a debit card payment too so perhaps okay either way.


    Do what works for you, of course. It would seem this judge's requirements haven't been modernized for awhile but if you're stuck, you're stuck.

    User thanked Elmer J Fudd
  • 8 years ago

    I finally have one person who pays her bills by cheque answer my post on my Facebook page. She only got her very first cell phone 2 years ago. We'll get her into the 21st century eventually. LOL It's a running joke at work. :) I just prefer to know right now, that the balance in my account is correct. Balancing chequebooks is a pain, then figuring in bank charges and fees etc., When I do online banking, it's all right there right now. I pay my bill. I see my balance. There have ever only been two payments that automatically come out of my bank account monthly: my house insurance and my property tax. I know $300 has to be in my account for those two bills. The rest is spending money (no more mortgage!!! YAY me!) Our joint account is for savings and bill payments. Only one auto pay comes out of that one: vehicle insurance payment. The rest is our bill payments which we control. I just think opening an app on my phone, or going on my computer to pay bills is so much easier. I do get some bills in my mailbox. A few I have sent to me electronically through epost.ca I just wait for an email notification I have a new bill. I can pay most of my bills through the company website as well, but I prefer to pay through my bank.


  • 8 years ago

    Debby, I have free checking so no charges or fees except my checks when I order them because I wanted the ones with duplicate copies. I don't have to wait until a check is cashed to know my balance as that money is spent and deducted regardless if it takes them a month to cash it. If I really want to know for some reason, I can go online and check to see if that particular check has cleared. When I get my statement from the bank I check everything, it really isn't that hard . :-).

  • 8 years ago

    One thing to be aware of when looking on line at your balance. There is a difference between debits/credits that state being processed vs the rest. Some banks do not consider the ones being processed as actually being in your account. There is a notice that banks release at least once a year that explains this. People who live from payday to payday plus others sometimes end up paying overdraft fees because of the way that bank processes incoming items. Some will process debits before credits which is where this most commonly happens. Couple of years ago this was addressed but the only change was that the banks had to give the notification and not process the credits first. For interbank, ACH, and wire transfers it will generally depend on what your bank balance is for the amount of the charge.

  • 8 years ago

    maifleur is talking about what happens when a bank puts a hold on a deposit. Different terms are used but the "book balance" could also be called "ledger balance" or "Account balance" while the other balance, funds that can be accessed and that are not subject to a hold, is "available balance". If a deposit or portion thereof is blocked for a few days, it could be in Account Balance but not Available Balance. When you look online, both numbers are typically shown. Banks update "ledger or account" balances only overnight, so that transactions that are processed during the day (ATM withdrawals, ACHs in or out) will be reflected in Available balance but not in Ledger or Account balances.


    In my experience, there's no hold put on periodically recurring deposits, like payroll payments or Social Security payments. People living from month to month are well served to run payments through a bank account because that's a way to get at the money the soonest. Such payments are usually available on the date payment is due, which should be when dispatched to the account. Similarly, if I do a transfer from an account in one bank to one of my accounts in another, the funds transferred are not subject to a hold and are immediately available.


    If you have a bank that doesn't make recurring payments that are deposited by transfer available immediately with no hold, find another bank.

  • 8 years ago

    No I am not Elmer. You have not read the annual statement that is sent to everyone with a bank account. Each of the three banks I have accounts with sends one. Some banks issue immediate credit. Others do not. The statement will tell you the sequence that debits and credits are processed.

  • 8 years ago


    When are funds available after deposit?


    Usually on the first business day after the day we receive your deposit. However, depending on the type and amount of your deposit, we may delay the availability of your funds. If we delay the availability of funds, we send you a notice and tell you when the funds will be available. A delay may occur under the following circumstances:

    • You deposit checks totaling more than $5,000 in one day
    • You redeposit a check that has been returned unpaid
    • We believe a check you deposit won't be paid
    • You've overdrawn your account repeatedly in the last six months
    • There is an emergency such as an equipment failure

    For more information on the circumstances under which a delay may occur, refer to theDeposit Agreement and Disclosures.

    Notice it does not mention a hold just how they handle deposits except for a few instances which most people will not have. You can click on the highlighted Deposit Agreement and Disclosures to read more. Some may consider it a hold to not process to an account immediately but a hold generally has to have someone higher than a clerk approve the release of a hold.

  • 8 years ago

    I only write a couple a year, mostly to the lawn service guys, or any work we have done around the house. I do get impatient sometimes when people pay with checks at the grocery store, especially if they don't start filling it out until after the total is given. The checks have to be filled out, scanned, sometimes the drivers licenses are checked. Sometimes they will stand there and write down the transaction details in the ledger area. Cards are so much faster! But I know it's my problem, not theirs.

  • 8 years ago

    A delay in the availability of a deposit is called a "hold".


    No, I don't read any annual disclosure items, of any kind. Should I? I also don't read software EULAs - end user licensing agreements. There's a long list of things that I don't think are worth the time to look at, you're welcome to believe differently.


    Before opening a bank account, if it matters, I ask in advance what their hold policy is and then observe what I experience. I don't think there's anything more to know. As I said before, anyone whose bank puts a hold in whole or part on recurring deposits, especially transfers, should find another bank. And anyone, other than in the course of running a business where there may not be a choice, who regularly receives checks in excess of $5000 from the same payor should try to get the funds paid by transfer, for the reasons previously described.


  • 8 years ago

    Chi, I know what you mean about getting impatient waiting behind someone. That's why I like the carbon copy. When standing in line I take that time to make the check out except for the amount. But sometimes, the ones paying with cards hold up the line for whatever reason or some hold up the line while they are trying to find a sale coupon on their phone. Seems there is no perfect solution...but unfortunately, that doesn't stop me from shopping! :)

  • 8 years ago

    If memory serves correctly, I've written about 5 checks in the past 5 years. Two were wedding presents and the others were for contracted labor with new vendors on the farm. Since it was only going to be once or twice I'd use them I didn't bother setting up a payment online. Otherwise I much prefer to pay it through the bank. I NEVER allow automatic payments unless it's absolutely required like Medicare. I make my payments and they cannot take more money from my account. Same with the credit card payment. One time only. For ones who don't accept electronic transfer, the bank sends a check on my behalf and they pay the postage and guarantee me that it will be there on time. If it's late, they pay any penalty. I'm not at the mercy of the postal orifice to deliver something at that rate, since I'm effectively insured. I don't do business with many places who do not take credit cards. I carry a check blank or two just in case but I have used one in about 10 years. My license tabs were paid with cash as I recall. I used to write checks for them but haven't for years. I've been meaning to do it via mail but that's another issue.

    I like my bank. I've been with them for decades. But I'm not as emotionally attached as are some! They're in business to make money, and I'm a customer. I like being able to call at any time and get someone who speaks English clearly. Their availability is vastly superior to any other around here. I'm fully satisfied.

    As pointed out guarding your routing and account numbers but passing out checks like campaign literature are contradictory since both numbers are on every check.