

long term health insurance
10 years ago
Featured Answer
Sort by:Oldest
Comments (7)
 10 years ago
Related Discussions
Question may be way too general...
Comments (3)Here in CA there is a program called HICAP (Health Insurance Consumer Advocacy Program, it is SUPPOSE to be a federal program. Their sole purpose is to help Consumers better understand their health insurance and to help fix any knots their insurance my be tied-up in. Very few people here know about the program, i spread the word when i can, perhaps there is a similar program in your state. web-search HICAP and see where they lead you or get in touch with your state's insurance commissioner....See MoreRetirement savings or long-term disability insurance?
Comments (4)Am in my late 50's. We don't have longterm disability insurance. It's a real gamble. My dad died young, was cared for at home by my mom--no real expense there. My mother just died this past November at age 85--she was at Thanksgiving dinner with us one night, and gone the next. Long term disability? Nope--she was still living independently in her own apartment. Now, note that in her 40's she had a number of health issues--anyone guessing would probably have figured that she'd either have died early, or have been disabled for a long time, and needed a lot of care in later years. Fact is, other than her regular check ups, visits to the podiatrist to care for her feet, and having her cataracts operated on, Mom hadn't had any serious medical treatment for over 20 years when she died. My father-in-law went very quickly, too--at age 82. He was still working as a plumber in November, spent a couple of months in the hospital, then died the beg. of February. I'm not saying you should or shouldn't get the insurance--only you can decide if it's right for you. But to my way of thinking, I don't see all that many people in my life who actually need longterm care. Most seem to either go quickly, or be able to manage their needs anyway. And the insurance companies are banking on the fact that their scare tactics will get lots of people to sign up--many who will never make a claim. For example, I've got an aunt who has had earthquake insurance for many years--no matter to her that we live in an area of the country that has never had a major earthquake in anyone living's memory. But they were more than happy to sell her a policy. I think she also has flood insurance--but she lives on the 6th floor of an apartment building. We also don't get floods of any size around here. That would have to be some departure from the norm for her to collect! And what about the safety of investing in an insurance company? What if the company goes out of business in years to come? Or waht if the funds are mismanaged or depleted by embezzlement. There is a huge scandal in the country right now regarding pre-paid funerals. People paid ahead to make sure their wishes would be taken care of, and many of the funeral homes have stolen those funds and families are having to come up with money to pay the cost of a funeral twice--the second time at a much higher price. Personally (and I'm not telling you what to do)--I prefer to save and control my own money. I'm not a fan of allowing others to take my funds--as in prepaid funerals, extra insurance, IRA's, etc. I do have one small SEP account, but only because I had a year where I needed some serious deductions, and that one was a reasonable way of keeping a few more of my own dollars. It's important to me to have the freedom to invest as I choose, and to move my money from here to there, depending upon what the economy is doing. I've just known too many people who have relied on others to nurture their savings, and lost everything. My sister is a case in point--worked for over 30 years for one company, was up in corporate management when the company was sold and dessimated by a larger one. She had a GOOD pension plan--but the funds were stolen by the new management, and when the company folded, she got a measely, one-time payout of $16,000!...See MoreLong term care insurance
Comments (69)Smart Money magazine published an article several years ago that argued against buying LTC in your 50s or earlier because the standard 5% inflation protection coverage would not keep up with the average 7% increase in nursing home costs. Basically, the earlier you buy the policy, the larger the gap that you will have between what your policy pays out and what the actual costs will be. Here are a couple of quotes from the article: "The 5% inflation adjustment is the industry standard, adopted by the National Association of Insurance Commissioners (NAIC) in the early 1990s. If the insurance industry were to adopt the 7% inflation figure that some predict, 'the cost would be prohibitive', says Tom Foley, an actuary with the North Dakota Insurance Department who chairs the NAIC's long-term care rate stabilization woking group." "The average age at which people buy long-term-care insurance is now about 65, and given the effects of inflation on your coverage, not to mention the uncertainty of health care costs and public policy 20 or 30 years from now, why buy it earlier than that? 'If there's a liklihood you might develop a health problem that makes long-term-care insurance expensive, you might want to buy it sooner', says Chuck Mondin of the United Seniors Health Cooperative, a nonprofit advocacy group. Otherwise, wait."...See MoreLong term care insurance?
Comments (31)chisue, insurance companies don't make money strictly off policy premiums. AIG's current headline news is a perfect example of this. When I worked at CIGNA (formerly Connecticut General, then they bought INA and changed their name), each of their 5 separate divisions was given an annual profit margin target to hit. This was called a "zero margin plus xx%". Note this was not a sales number, it was a "quick and dirty" percentage of how much revenue minus division expenses they made annually. My boss (one of the regional VPs with a shot at the division presidency) got interested in exactly where this target number came from. He learned that what CIGNA called "zero margin" was actually a base 15% profit margin. CIGNA could earn 15% off its money, through investments and such things as real estate development (for instance they bankrolled Foster City, a landfill development in the SF Bay Area that was considered risky at the time, but is now a desirable mixed-use suburb, selling it after a few years for a hefty profit), without ever writing another insurance policy. Therefore, their divisions had to earn OVER that 15% profit margin, to be worth expending corporate funds for. This is why insurance companies go in and out of market niches - they tend to keep a fairly conservative eye on what their profit margins are on each line of business. When people are discussing the stock market, the majority of money in it is institutional. Insurance companies are a very large part of that. They are even better than banks at leveraging their money. We used to make jokes about actuaries, but insurance companies realistically suvive on the number-crunching abilities of their actuaries. Like developers in a software company, they are what actually drives the financial corporate engines....See More- 10 years agolast modified: 10 years ago
- 10 years ago
- 10 years ago
- 10 years ago
- 10 years ago
Related Stories
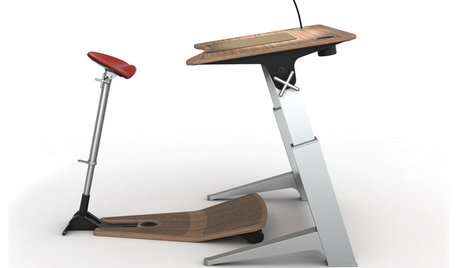
HOME OFFICESStand-Up Desks Rise to Health Challenges
Sitting all day may be wrecking your health. Are you going to stand for that?
Full Story
FEEL-GOOD HOMEHow to Treat Your Home to a January Health Kick
Your house is an extension of you, so give it a reboot this month to ensure that it’s fit, happy and ready for the year ahead
Full Story
HEALTHY HOMEHow to Keep Water Vapor From Ruining Your House and Your Health
We help you find out when it’s happening, what it means and how to fix it
Full Story
DECORATING GUIDESImproving a Rental: Great Ideas for the Short and Long Haul
Don't settle for bland or blech just because you rent. Make your home feel more like you with these improvements from minor to major
Full Story
WORKING WITH PROSHow Long Is Your Contractor on the Hook?
Understand how a warranty protects homeowners from shoddy work — and builders from being liable for their work for forever and a day
Full Story
HOME INNOVATIONSConsidering Renting to Vacationers? Read This First
More people are redesigning their homes for the short-term-rental boom. Here are 3 examples — and what to consider before joining in
Full Story
WINTER GARDENINGPruning Secrets for Exquisite Roses
Encourage gorgeous blooms year after year with this time-tested advice on how to prune your rosebush in winter for health and shape
Full Story
FALL GARDENING7 Reasons Not to Clean Up Your Fall Garden
Before you pluck and rake, consider wildlife, the health of your plants and your own right to relax
Full Story
FARM YOUR YARDIf You Have Room for Only One Summer Crop ...
Get an edible that’s long on flavor even if you’re short on space, with a long-time gardener’s favorite picks
Full Story
FRONT YARD IDEAS10 Ideas for a Front-Yard Edible Garden Your Neighbors Will Love
Choosing attractive, well-mannered plants and sharing the bounty will go a long way toward keeping the peace
Full Story
User