

Soc sec statements, do u save & why?
10 years ago
Featured Answer
Sort by:Oldest
Comments (9)
Related Discussions
Need some retirement saving advice please.
Comments (18)So do I. Congratulations on realizing your need and setting out on this journey of learning about your money and how to work with it effectively. There are two basic issues ... one is your income and how to deal with it to make each of those dollars coming in work most effectively. The other is your asset base and how to manage it to make it grow well, working harder for you than for the other guys ... and avoiding having too much of snipped off by the purportedly big-deal managers to slip into their pockets. Better to learn what you're doing, over the years, and become your own manager! Pay yourself those fees that they charge (probably wise to deduct the cost of some of your mistakes, as you learn). In the investment group that I've attended monthly for about 7 years, we call them the tuition fees in the University of Learning How to Manage Your Own Money! I bought some equity-based mutual funds over 20 years ago, charging 2.5% of the value of the current asset value of the account, annually. When you multiply 2.5 by 20+ ... what do you get? 50% of the value of my asset, right? Is that the original asset amount? No - the creeping value of the asset as it grew, over time. I started a thread (I think over on KT) a couple of weeks ago asking whether people had ever seen stock certificates grow like rabbits! Had a person bought 1 share of JNJ at the beginning of 1970 (I'm using this for illustration, not suggesting that you should buy it, or not buy it) about how many shares would they think that they'd own, now? If you go to Yahoo->Finance and put JNJ in the "Get quotes" box at upper left, you'll get a page that shows a lot of info about current situation of the shares, including a chart at lower right of the stock price movements today. Clicking at a long-term period under that chart will show you share prices over your choice of various periods ... plus info about several stock splits - twice 3:1, and 4 times 2:1. What does that produce? 1->3->9->18->36->72->144 ... right? Price in 1970 $180./share (in dollars each of which was "worth" a lot more than each dollar is now). Current price about $63.00. That is, $180. grew to about $9,072. How do you like them apples? Not only that ... I read somewhere a while ago about a numberof stocks which had increased their dividend annually for 25 years ... I think JNJ has increased theirs annually for 40 years, if I'm not mistaken. Which adds some sugar to the applesauce, right? When did you ever hear of a Guaranteed Investment Certificate acting like that? Also wise for you to learn to deal with both income and assets in a tax-effective way. If you can reduce taxes now, often a good idea to do so, if the system at issue is useful in your case. Deferral is frequently a good idea, as well, when available. In Canada, a number of people look at the current rate on a GIC and at the rates paid by a stock, and say they like the interest rate better than the dividend rates usually offered. But when Canadians earn a dividend on a Canadian stock, the tax rate used to be lower, and last year the system of calculation changed to make it even lower again. I can't believe how many Canadians I've run into over the years who didn't know that! Quite often ignorance carries a substantial price. I think that I've said to thousands, over the years, that learning how money works is an interesting hobby ... **that pays well**!! (I've said it so often, around here, that I think that people must be getting sick of hearing it!) Not only that, if you put your dollars into a investment where their numbers are guaranteed not to shrink ... they're almost always guaranteed not to grow either. I bought a stock over 40 years ago for about $4. and change, which at that time paid about a (tax-advantaged) nickel or a dime. Over the years the value of that stock has gone up, down and sideways. I could have sold it last May for about $107. ... and it pays me an annual dividend now of $3.48. There's one catch - it has been doubly involved in the U.S. sub-prime mortgage debacle. The share price dropped to the $80.s, then recovered to near $100., then slipped back into the $80.s ... and in the past few weeks, as the sub-prime issue got more complex, far-reaching and distressng, the share price dropped down through the $70.s, into the $60.s, closing since the first of the year in the $60.s ... and I suspect that the dividend rate will likely be cut. Am I about to sell it? No. I paid $4.20 over 40 years ago, and if I sell now, I deduct the $4.20 amount that I paid from the current $68.20 or so, leaving me with $64.00 capital gain. I divide that by 2, leaving me with $32.00 on which I must pay tax at my usual rate (i.e., added to the top of my other income this year). But it does leave me with the other $32.00 realized free of tax. However, I'm getting close to 80 years of age (79 next Wed.) and my current tax bracket is lower that will be the case if I leave all of those assets intact till I kick the bucket - for then some of them will be taxed at lower rates, but after that's used, others will be taxed at higher rates until they get to the top rate, and my executor will have to pay that on some of those realized capital gains, then. Also ... since I have no spouse (to which the tax-deferred retirement account could be transferred, tax-free at the moment, to be added to her assets, to provide her with income and on her death to have the residue added to her income and taxed then, at whatever rate) they'll be added to my income in that year, as well. Likely taxed at top rate. I've thought of selling some of the stocks that I've held for years, in order to have the taxable portion of the capital gain taxed now, at my usual lower rate ... ... but if I do that, I have fewer dollars to re-invest, to go on not only growing, but adding to earnings in those years, until my demise. As it is, I add those $3,000. or so that I'm required to withdraw from my tax-deferred retirement account annually to my annual income. Do you think that I should follow the advice of some hot-shot financial advisors who tell how to get that payment out tax-free? Borrow $50,000. to invest it in a variety of stocks, using well over $100,000. (I wish!) of stock certificates as collateral, making it a fully secured line of credit, at interest of 6%, i.e $3,000. per year, using my $3,000. annual payout from my retirement account to pay the interest. My deal with the lender is that I pay interest only on the loan. As the loan is used for investment, the interest is deductible. As an old fart that doesn't want to take heavy risks, I invest in some quality Canadian stocks - paying about 3% interest, and as they are taxed at low rate, I have about 2.5% after-tax income, which in other circumstances I would use to help pay the interest on the loan. Suppose I'd borrowed that money 15 years ago, paying interest only through those years. If my Dad died and left me $50,000. as a legacy, and I took it to the bank to pay off the loan, how much would I owe them? That'd be $50,000., right? That would have bought a lot of good things, 15 years ago ... much more than now. I gained from inflation. Suppose you'd put $50,000. into the bank, 15 years ago, and the bank paid you the agreed upon rent on your money, in the years between ... and you went to collect the value of your GIC today ... how much would the bank give you? Right! Exactly $50,000. That would have bought a couple of good cars, 15 years ago ... not now. I gained from inflation ... you lost. Such strategies should be used with discretion, taking into account various possible scenarios, some of them quite unattractive, with the operator able to deal with them without serious inconvenience. I never want to see my friends get margin calls on such loans, unless they're able to meet the shortfall, whether with other assets ... or immediate cash. Good wishes for using both your income and assets increasingly skillfully! As you have further questions, feel free to ask. If some of them seem a bit too private for you to feel comfortable with discussing in this public place, I'm sure that several of us who have responded here would be pleased to offer you our opinions should you contact us privately. ole joyful...See Moredigital statements, bills, etc.
Comments (32)After working for UCSF for 7 years (not all full time and a maternity leave in there), I moved to another state after doing careful calculations about being "vested" in the Univ of CA retirement plan. "Vesting" was based on 5 years of 40 hr/wk work and I worked 36 hr weeks (3 x 12 hr) and took some time off for grad school and a baby. After I left I was told that I was not vested due to inadequate hours; this was apparently due to a clerical error I had suffered for the first few months I worked there, when they erroneously put me down as a "per-diem" (as opposed to "benefitted") employee. In order to prove that that was in error, I had to provide those paystubs including the one with the "correction". I'm so glad that I had obsessively filed those paystubs for direct deposit in chronological order and was able to put my hand on it, copy it and mail it to them. As a result, I will have several hundred dollars each month in retirement that I wouldn't have otherwise. Retirement's a long way away, but not something to be toyed with. Besides, I'm sure my daughter will laugh at the "measly" $18/hr I was being paid at the time as a new nurse. When my father died, I found sheets of yellow legal paper in his files accounting how much money he had found on the street since the 1950's: "1972 79 cents, 1973 $10.41" etc. Although amusing, it wasn't needed, but all his files were exceedingly better maintained than mine. I am nervous about going to "paperless" systems in case I were to be hit by a truck tomorrow. My mother would need an extensive list of passwords and websites to access my retirement plans (to even know about them) and other accounts. My ex is not a reliable source of info, and doesn't have a clue about what accounts I now have (and wouldn't help her if he knew). You're not supposed to write down those passwords after all. My mother has been made the beneficiary of my retirement accounts, because I know she will properly use the money for my daughter. I will change all of that in 10 years or so when DD is old enough....See MoreTwig mirror is in, what do u think?
Comments (33)Cindy/les - TV over FP was thought through and ruled out due to hieght issues, even if its angled. TV was temporarily infront of the FP on the hearth before I bought the TV stand. I cant tell you how good a position that was, it worked out perfectly from every direction. But for some reason I never thought of it as a permanent location for it. Will think it through, but will have to keep a cabinet on each side for the components and game consoles. I cant do builtins on either side of the FP as the right side is leading towards the stairs and they might be blocking the way. I do plan to paint the mantle dark, something similar to the floor color or may be black, if you guys have a paint suggestion please share....See More28 Tips To Save Money
Comments (5)On #s 15 & 16, I think it's important to point out that often the alternative to refi and the like is simply pay down the principle! Especially if you're early in the mortgage, every nickel you pay toward the principle means the balance of the loan's interest on that nickel goes into your pocket. Ol' Joyful, I'll need some of your expertise here, but could you figure a rough calculation of an average type house loan, average refi costs applied to the current loan and how that would compare in the end? I think it'd be interesting. Also, said before, but often people think they "need" a new car and don't consider if they put some money into the old one, it'd save in the long run. Remember, new cars have higher insurance and license costs so there's more than the initial price to consider. I would take a bit of issue too with the convenience store avoidance. You could actually save money if wise. Often, convenience stores sell eggs, milk, bread etc at very low prices, often far less than the markets. Plus it's not a special trip, saves time plus there can be (tho not guaranteed - it's up to you) fewer impulse buys. The longer you're in the grocery store, stats say you'll spend more. Again, it's how savvy you are, but be careful. #18 (Shudder) Buyer's Brokers are seldom a good thing. Let's face facts, no real estate agent/realtor or the like works FOR the buyer! Who pays them? The seller. How do they get paid more? By "benefitting" the seller. There's no way the buyer benefits from realtors. The fewer the better in most cases. Why? Because you can often negotiate the realtor fees. If you have one realtor taking the entire commission, it's far easier to negotiate them down than to negotiate with multiple agents and try to negotiate down when they're getting 1/4 or less of the commission. Beware of this statement and check into these claims. You're far better off to have a good real estate attorney on your side. S/He'll be working for YOUR benefit. Mine found problems in the paperwork and embarrassed the daylights out of the stack of realtors, closers and the like at my closing! It was hilarious! Now as for the inspector, yes, that can be worthwhile, but don't use one recommended by the realtor (kickbacks) and make sure you know what they're inspecting, their qualifications and the like. A good alternative can be a trusted friend with qualifications. Hire like any professional. Realize, though, that the inspectors DO NOT GUARANTEE the house! So if they overlook something, it's not their fault or responsibility and they won't be doing anything for you so know what you're getting. A title examination, especially of abstract properties, can be very important especially if you don't know how to read an abstract. Torrens is less problematic. Buying a home brings up a pandora's box of potential problems and far too many to go into here, but there's some things to be careful of. #21 Consumer Reports is a pet peeve of mine. They're often very biased in their reporting. Plus, keep in mind that they do not "test" ALL models and versions, even of similar products! Do you realize that the washer you buy at Home Depot is different than the one you buy at Best Buy and they're both different than the one you buy from a mom-n-pop dealer? That can have significant differences in the specs and needs. One can have cycles and features the other doesn't. Don't get caught up in the CR myth. Read their magazine with a shaker full of salt and do far more research than CR. You'll be doing yourself a favor. That's enough for now. There's more opinions coming, I'm sure! :) Happy saving all! Enjoy the frugal season!...See More 10 years ago
 10 years ago
 10 years ago
 10 years ago
 10 years ago
- 10 years ago
 10 years ago
Related Stories
SAVING WATER11 Ways to Save Water at Home
Whether you live in a drought-stricken area or just want to help preserve a precious resource, here are things you can do to use less water
Full Story
LIFERetirement Reinvention: Boomers Plot Their Next Big Move
Choosing a place to settle in for the golden years? You're not alone. Where boomers are going and what it might look like
Full Story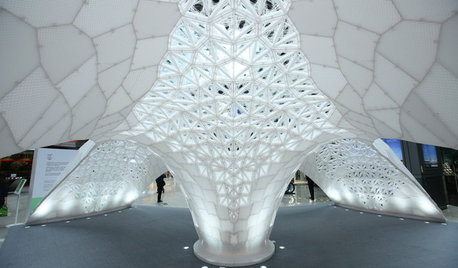
ARCHITECTUREWhat the Future Holds for 3D Printing in Architecture and Design
Designers worldwide are creating 3D-printed buildings, furnishings and materials. Will we be seeing this trend in our homes?
Full Story
socks