

Do stocks held by me belong in Planners portfolio?
9 years ago
Featured Answer
Sort by:Oldest
Comments (26)
 9 years ago
Related Discussions
Financial Planner
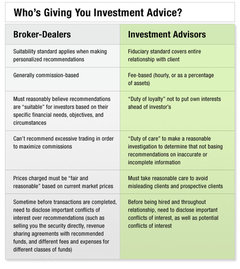
Comments (12)Hi azmom, Anyone uses a financial planner? You bet... I've surrounded myself with them (but it's my industry anyway... and I have an "immersive" nature as well....) What kind of service/assistance do you recieve from your financial planner? There are many angles to financial planning... and although I know of firms that CAN offer something from every perspective, I have RARELY FOUND* a single individual who can effectively "step back" and look at the entire big picture and actually apply the various critical knowledge details to map out a full, comprehensive plan. (*The ONLY exception being "fee only" professionals who are not compensated on transaction frequency or account sizes... but either hourly fees (no incentive against your best interests... but really no incentive FOR your best interests either,) or an annual percentage of your total Net Worth GROWTH (which means they win when/if you win, and get less, or nothing, if you do not win... little or no compensation for financially 'treading water.') From a very HIGH LEVEL, GENERAL perspective, the areas that need to be coordinated and planned are; A) Assets (this is what much of the industry solely focuses on,) B) Risk Coverage (mostly done with insurance... which, unfortunately, is too rarely "planned" and too frequently "pushed." Everyone who is beyond being single, renting a shared room and earning minimum wage, needs SOME degree of protective coverage... The more you have (income, assets, dependents, etc.,) the more you need further levels of properly fit coverage... however, as with food "more is not necessarily better." Being properly custom FIT with coverage is the critical piece a planner needs to be able to do... and that changes (just like human bodies being fit for clothes) over time. C) Safe Savings (and the avoidance of 'deadening' the family portfolio by putting TOO MUCH in 'safe' savings when it may be neither safe, nor properly earning what the family needs it to earn.) D) LEVERAGE/DEBT Management. Eliminating 'naked debt' is critical... but too often confused with the use of 'tax-preferenced asset leverage.' Debts such as consumer credit generally reduce the family net worth and safety, while properly used tax-preferenced asset leverage (mortgages and business credit) generally increase family net worth and safety. The critical issue is how to know which is which, and how to treat them (which are polar opposites.) E) Tax Planning. Waiting until it's time to do your tax returns before you pay attention to your tax details is analogous to going to a single aerobics class once a year and wondering why you can't catch your breath. Some people are comfortable (or willing to struggle) with the basic forms of tax returns once a year... but MOST people are confused & overwhelmed by the moving-target details of structuring your financial life so that you are "least bitten" by the tax wolves. Just the difference of keeping 10% more of what is yours every year (and having it work in compounding returns) is a HUGE piece in the puzzle of what you are left with at retirement... and having someone who lives, eats, and breathes (and stays sane) in the world of taxes and the IRS code changes is a critical support. How did you find him/her? A) I lurk (and participate) at various financial communities online (like this one... though I don't know any other planners here...) B) I ask those I know (and am impressed by) for introductions to others THEY know in ancillary expertise fields. What are your expectations of the service? Someone who LOVES the corner of the industry they specialize in, and just devours the concepts on an ongoing basis. I seek "no b.s." sincerety and integrity... someone I COULD trust to toss my house-keys to if they were in town while I was away on vacation. Someone who has the same perspective on comprehensive and balanced planning... same ideas about life, and what "retirement" does and does not mean... and the ability to truly LISTEN, and if they do not understand, to ASK.... What is the fee structure? Is it worthwhile to use the service? Above are my perspectives on BEST fee structures. Since I have no single "captain" (but reserve that hat for myself) I have different incremental arrangements with the players on my 'financial support board.' For anyone desiring to NOT wear the "captain's hat" I would recommend SELECTING a 'captain' (or "lead advisor") with the idea that they will NOT be relied on to be the "one size fits all specialist" (which is simply unrealistic) but rather the "quarterback" for the professional team YOU OWN who are all facing the same goalposts that you are, and win when you win. Is it worthwhile? If you choose your professionals carefully, and stay in regular contact so THEY know they are taking you where you want to go... DEFINITELY! Cheers, Dave Donhoff Strategic Equity & Mortgage Planner...See MoreMet with financial planner yesterday (retirement)
Comments (42)I'll be happy to help you with this. First of all, there are two different reduction calculations: one for the basic insurance and one for the option B insurance. It sounds like your question pertains to the basic insurance. As I stated in an earlier post, it appeared that your husband had calculated the basic insurance premium based on a 50% reduction at age 65. What this means is that starting with the 2nd month following his 65th birthday, the amount of his basic insurance will decrease 1% per month for 50 months until the amount of the insurance is only 50% of what it was when he retired. So, if he started with $150,000 of basic life insurance, it would end up being $75,000 when he is 69. The amount that he pays will change from .925 per thousand to .325 per thousand at age 65 and will continue for as long as he lives. He could also choose the "no reduction" option, in which case the basic insurance would never be reduced and the full $150,000 would be payable upon his death. However, instead of paying .925 per $1000, his premium would start off at more than double that amount. He would be paying $2.155 per $1000. Finally, he also could choose the 75% reduction which of course is the cheapest. He would start off paying only .325 per $1000, but at age 65 the amount of basic life insurance would begin reducing at the rate of 2% per month until only 25% was left. So, if he started with 150,000 worth of basic insurance, he would be left with only 37,500 by age 68. However, he would stop paying premiums at age 65 and the 37,500 worth of insurance would be free for the rest of his life. Similar choices must be made with regard to the optional insurance, but I believe that those choices don't have to be made until he is 65. Let me know if you want me to go into detail about the optional insurance (which represents about $300,000 of his coverage). I hope that this explanation has helped somewhat....See MoreFinancial Planners
Comments (4)Some years ago a local psychiatrist consulted me about retiring early. Afer a consultation, my advice was that not only could he not retire early, it would keep him busy to retire at the regular age (he was in an institution and carried on private practice - which he did not want to continue after retirement). How come? He hadn't taken any account of the ongoing erosion of the value of his underlying asset due to inflation. I gave him several proposals - and he said not to give him all of those alternatives - just tell him what to do. I said that no one cared as much about his money as he - no financial planner or anyone else would agree to cover half of his potential losses. So it would be best if he learned some things about how money works. He said that learning how money worked was too much for him. I said that he had good mental capacity between his ears (or he couldn't have gone as far as he had in the medical field). While the money business is complex, the issues that affect most us individual investors are not so terrible. Looked at all at once, it does look hard - but I've told a number of people that it's a bit like a family using a loaf of bread. Mom buys a loaf and puts a few slices on the table. If Jimmy, having run around all afternoon and feeling ravenous, stuffs a whole slice into his mouth at once, he has a problem. Taken a bite at a time, even an old fart like me can work his way through a whole loaf in a few days. Don't let the money issue, looked at as a whole, intimidate you. Learn how money works - a bite at a time. Good wishes as you embark on that - or other interesting - adventures. joyful guy/Ed...See MoreStock Market Worries
Comments (49)May I suggest that you keep things in perspective, folks? If you spent years in post-secondary education and had some interim jobs before getting on career track and really hot (I thought that I wrote "got") going at 30, and now at 60 are looking at retirement, whether voluntarily or forced ... you've had a 30 year career. Take it from this guy who was 90 last year ... you may be retired as long as you worked! Have you heard which segment of life has been the fastest growing, in our part of the world, in recent years? The folks over 100! (Granted ... the calculation started from a not-large base). The early years of retirement are expensive, what with all of that pent-up energy being released in kicking up your heels, running around and having fun ... then come the middle somewhat quieter, more relaxed (thus somewhat less expensive) years. Possibly somewhat enhanced, finance-wise, by downsizing from major house to more modest digs, thus freeing up some meaningful assets for investment. Usually there are substantial costs associated with the latter years of our lives, living in a retirement home, then assisted care, and then nursing homes ... and while one can sing while there, if one chooses - you don't get to stay there for a song! Many advisors suggest that a substantial portion of money which you don't expect to need for about ten years or more can well be invested in qualty eguities. Eating my own cooking, as I do - well over two thirds of my investments are equity-based. Most of the mutual funds, most held for a number of years, charge about 2% a year as management fees. ETF fees are substantially lower. Over half of my portfolio is in individual stocks owned directly. One that I bought over 50 years ago for $4,25 a share, paying 10 or 12 cents a year dividend, was (supposedly) "worth" $107. in 3007, paying $3.08 dividend. I don't know what "worth" is - what I mean is that that is the price for which I could have sold it at that time. The price available in 2008 dropped to $40., as that company was heavily involved in the financial fiasco operational at the time. Should have had the courage to buy more (at what precise time, pray tell?) ... but didn't. Some said they'd cut dividends: they didn't, but there was no increase for 4 years. Share prices grew to around $120. a few months ago, payng $5.76 annual dividend - recent offer is about $68. Estimate cost in a year just over $100. Over those 50+ years of ownership - haven't paid a nickel to any manager's fee. May invest some soon, some more later: no one knows where the bottom will be. In what I think to be a more valuable company for the price. Many advisors suggest to invest equal number of dollars on a regular interval, called "dollar cost averaging": one gets fewer shares when prices are high, more when prices are low. Good wishes for making wise use of your dollars in a long-term plan. Better to have dollars left at the end of the years ... than years left at the end of the dollars! Who'll then pay for the funeral/plot/headstone? ole joyful...See More- 9 years agolast modified: 9 years ago
- 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years ago
- 9 years ago
 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years ago
- 9 years agolast modified: 9 years ago
- 9 years ago
- 9 years ago
- 9 years agolast modified: 9 years ago

Related Stories
MOST POPULARDecorating 101: How Much Is This Going to Cost Me?
Learn what you might spend on DIY decorating, plus where it’s good to splurge or scrimp
Full Story
ORGANIZINGHow Much Stuff Is Enough?
Play the numbers game to streamline your belongings, for a neater home and a less-stressed you
Full Story
MOVINGShould It Come With You When You Move?
Ask these 4 essential questions about every one of your belongings before you move into a new space
Full Story
WORKING WITH PROS8 Questions to Ask Yourself Before Meeting With Your Designer
Thinking in advance about how you use your space will get your first design consultation off to its best start
Full Story
ORGANIZINGDo It for the Kids! A Few Routines Help a Home Run More Smoothly
Not a Naturally Organized person? These tips can help you tackle the onslaught of papers, meals, laundry — and even help you find your keys
Full Story
MOST POPULARHow to Choose the Right Kitchen Sink
Learn about basin configurations, sink shapes, materials and even accessories and specialty sinks
Full Story
DOORSKnow Your House: Interior Door Parts and Styles
Learn all the possibilities for your doors, and you may never default to the standard six-panel again
Full Story
LIFEThe Beautiful Thing About Dad's Chair
My father had his own spot in the house. His father had his own spot. Now I have mine
Full Story
BATHROOM DESIGNSpotted: Refrigerators in the Bathroom
You read that right. Before you protest, here are seven good reasons why people are chilling in the bath
Full Story
ECLECTIC HOMESHouzz Tour: Parisian Modern Updates for a Toronto Coach House
Iconic furniture, creative groupings and bold colors turn a short-term Canadian rental into a knockout
Full Story
sushipup1